


Page 21 - LCP Annual Report & Accounts 2026
P. 21
NET ASSETS
The Group continues to actively manage its interest rate exposure through the use of derivative instruments. During the year the Group has entered into or acquired interest rate swaps based on principal amounts totalling £168.3m (FY25: £76.5m) and €75.4m (FY25: €45.5m) and interest rate caps/collars based on principle amounts totalling £Nil m (FY25: £30m), €Nil m (FY25: €2.5m).
The bank raises all of its debt through bilateral secured facilities with major banks, with the exception of some loans from an insurer and some lease finance in Poland.
EVENTS AFTER THE BALANCE SHEET DATE
As at 31 March 2026, the Group had £214m (FY25: £148m) of bank debt falling due within one year or on demand. As at September 2026, £133m has been refinanced to December 2028, with the remaining £82m in negotiation. Further details of loans and borrowings can be found in Note 25.
            £1600m £1400m £1200m £1000m
£800m £600m
FINANCING
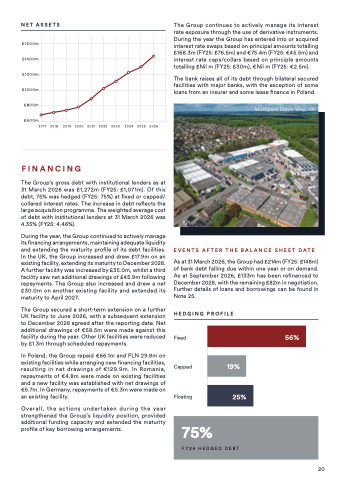
The Group’s gross debt with institutional lenders as at 31 March 2026 was £1,272m (FY25: £1,071m). Of this debt, 75% was hedged (FY25: 75%) at fixed or capped/ collared interest rates. The increase in debt reflects the large acquisition programme. The weighted average cost of debt with institutional lenders at 31 March 2026 was 4.35% (FY25: 4.46%).
During the year, the Group continued to actively manage its financing arrangements, maintaining adequate liquidity and extending the maturity profile of its debt facilities. In the UK, the Group increased and drew £17.9m on an existing facility, extending its maturity to December 2028. A further facility was increased by £35.0m, whilst a third facility saw net additional drawings of £45.9m following repayments. The Group also increased and drew a net £30.0m on another existing facility and extended its maturity to April 2027.
The Group secured a short-term extension on a further UK facility to June 2026, with a subsequent extension to December 2028 agreed after the reporting date. Net additional drawings of €58.5m were made against this facility during the year. Other UK facilities were reduced by £1.3m through scheduled repayments.
In Poland, the Group repaid €66.1m and PLN 29.8m on existing facilities while arranging new financing facilities, resulting in net drawings of €129.9m. In Romania, repayments of €4.8m were made on existing facilities and a new facility was established with net drawings of €5.7m. In Germany, repayments of €5.3m were made on an existing facility.
Overall, the actions undertaken during the year strengthened the Group’s liquidity position, provided additional funding capacity and extended the maturity profile of key borrowing arrangements.
 Multipark Eldon Way, UK
 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026
 HEDGING PROFILE
   Fixed
Capped
Floating
56%
 19%
25%
  75%
FY26 HEDGED DEBT
20


