


Page 61 - LCP Annual Report & Accounts 2026
P. 61
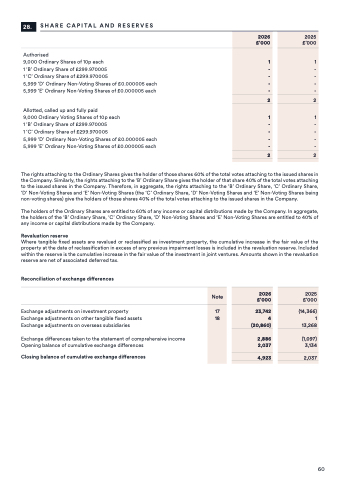
28.
SHARE CAPITAL AND RESERVES
 2026 £’000
  1
-
-
-
-
2
1
-
-
-
-
2025 £’000
1
-
-
-
-
  2
  1
-
-
-
-
  2
2
    Authorised
9,000 Ordinary Shares of 10p each
1 ‘B’ Ordinary Share of £299.970005
1 ‘C’ Ordinary Share of £299.970005
5,999 ‘D’ Ordinary Non-Voting Shares of £0.000005 each 5,999 ‘E’ Ordinary Non-Voting Shares of £0.000005 each
Allotted, called up and fully paid
9,000 Ordinary Voting Shares of 10p each
1 ‘B’ Ordinary Share of £299.970005
1 ‘C’ Ordinary Share of £299.970005
5,999 ‘D’ Ordinary Non-Voting Shares of £0.000005 each 5,999 ‘E’ Ordinary Non-Voting Shares of £0.000005 each
The rights attaching to the Ordinary Shares gives the holder of those shares 60% of the total votes attaching to the issued shares in the Company. Similarly, the rights attaching to the ‘B’ Ordinary Share gives the holder of that share 40% of the total votes attaching to the issued shares in the Company. Therefore, in aggregate, the rights attaching to the ‘B’ Ordinary Share, ‘C’ Ordinary Share, ‘D’ Non-Voting Shares and ‘E’ Non-Voting Shares (the ‘C’ Ordinary Share, ‘D’ Non-Voting Shares and ‘E’ Non-Voting Shares being non-voting shares) give the holders of those shares 40% of the total votes attaching to the issued shares in the Company.
The holders of the Ordinary Shares are entitled to 60% of any income or capital distributions made by the Company. In aggregate, the holders of the ‘B’ Ordinary Share, ‘C’ Ordinary Share, ‘D’ Non-Voting Shares and ‘E’ Non-Voting Shares are entitled to 40% of any income or capital distributions made by the Company.
Revaluation reserve
Where tangible fixed assets are revalued or reclassified as investment property, the cumulative increase in the fair value of the property at the date of reclassification in excess of any previous impairment losses is included in the revaluation reserve. Included within the reserve is the cumulative increase in the fair value of the investment in joint ventures. Amounts shown in the revaluation reserve are net of associated deferred tax.
Reconciliation of exchange differences
Exchange adjustments on investment property Exchange adjustments on other tangible fixed assets Exchange adjustments on overseas subsidiaries
Exchange differences taken to the statement of comprehensive income Opening balance of cumulative exchange differences
Closing balance of cumulative exchange differences
  Note
 17
18
 2026 £’000
 23,742
4
(20,860)
 2,886
2,037
 4,923
  2025 £’000
 (14,366)
1
13,268
 (1,097)
3,134
 2,037
   60


