


Page 53 - LCP Annual Report & Accounts 2026
P. 53
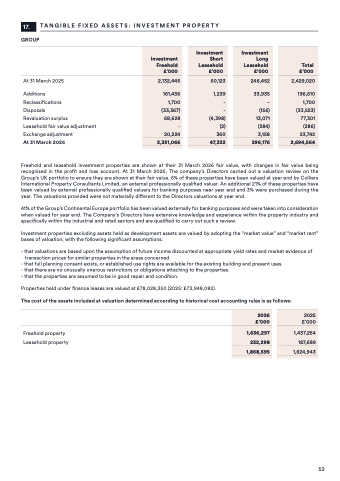
TANGIBLE FIXED ASSETS: INVESTMENT PROPERTY GROUP
At 31 March 2025
Additions
Reclassifications
Disposals
Revaluation surplus
Leasehold fair value adjustment Exchange adjustment
At 31 March 2026
Freehold and leasehold investment properties are shown at their 31 March 2026 fair value, with changes in fair value being recognised in the profit and loss account. At 31 March 2026, The company’s Directors carried out a valuation review on the Group’s UK portfolio to ensure they are shown at their fair value. 6% of these properties have been valued at year end by Colliers International Property Consultants Limited, an external professionally qualified valuer. An additional 21% of these properties have been valued by external professionally qualified valuers for banking purposes near year end and 3% were purchased during the year. The valuations provided were not materially different to the Directors valuations at year end.
41% of the Group’s Continental Europe portfolio has been valued externally for banking purposes and were taken into consideration when valued for year end. The Company’s Directors have extensive knowledge and experience within the property industry and specifically within the industrial and retail sectors and are qualified to carry out such a review.
Investment properties excluding assets held as development assets are valued by adopting the “market value” and “market rent” bases of valuation, with the following significant assumptions:
- that valuations are based upon the assumption of future income discounted at appropriate yield rates and market evidence of transaction prices for similar properties in the areas concerned.
- that full planning consent exists, or established use rights are available for the existing building and present uses. - that there are no unusually onerous restrictions or obligations attaching to the properties.
- that the properties are assumed to be in good repair and condition.
Properties held under finance leases are valued at £78,028,350 (2025: £73,948,082).
The cost of the assets included at valuation determined according to historical cost accounting rules is as follows:
Freehold property Leasehold property
17.
   Investment Freehold £’000
 Investment Short Leasehold £’000
 Investment Long Leasehold £’000
 2,132,445
 50,123
 246,452
161,436
1,239
33,935
1,700
-
-
(33,367)
-
(156)
68,628
(4,398)
13,071
-
(2)
(284)
20,224
 360
 3,158
 2,351,066
47,322
296,176
    Total £’000
 2,429,020
196,610
1,700
(33,523)
77,301
(286)
23,742
 2,694,564
      2026 £’000
 1,636,297
232,298
 1,868,595
  2025 £’000
 1,437,254
187,689
 1,624,943
   52


